New Flood Performance Certificates to Help Homeowners Reduce Flood Risk
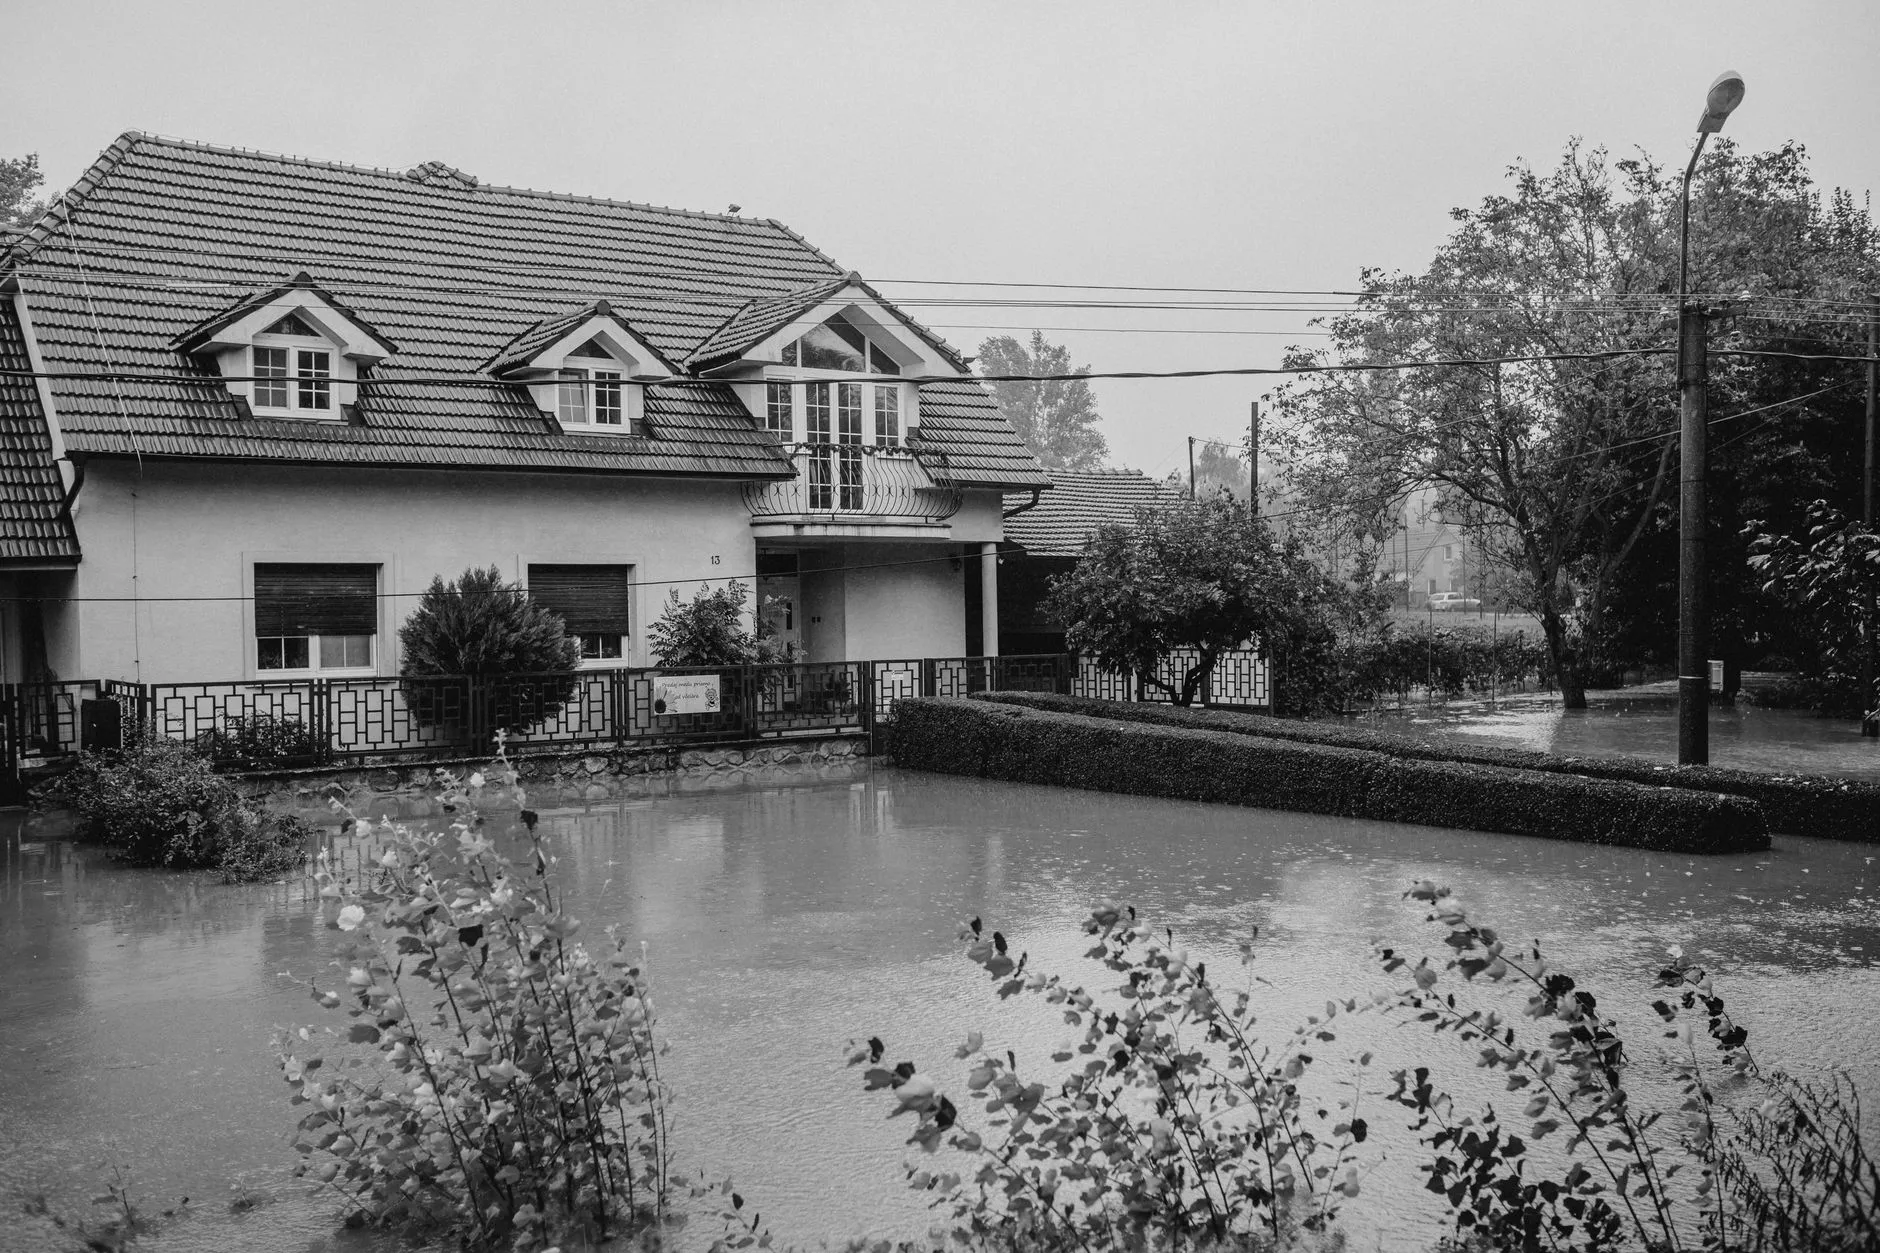
Flooding already costs UK households hundreds of millions of pounds each year in damage, disruption and insurance claims. However, property-level information about flood resilience remains patchy. A homeowner might know their area sits within a flood zone, yet lack clarity on how vulnerable their specific building is or which protective measures would make the most difference.
That gap is now being addressed. Flood Re and the UK Government are developing Flood Performance Certificates to provide a standardised way of assessing and communicating how well a property can withstand flooding. The certificates would work similarly to Energy Performance Certificates, creating a recognised rating that homeowners, insurers and lenders can all understand and act upon.
Pilot schemes are scheduled to begin in high-risk areas during 2026. Further testing will follow in 2027. The aim is to establish whether a single certificate can reliably serve multiple audiences, from families considering protective measures to mortgage providers evaluating long-term insurability.
For businesses involved in construction, property management or insurance-linked supply chains, the development carries commercial significance. A new, mandatory rating system could influence property values, retrofit markets, insurance pricing and lending criteria across flood-prone regions.
What a Flood Performance Certificate would contain
The proposed certificates go beyond identifying whether a property lies in a flood zone. Instead, they would record what happens when water reaches the building and how resilient the structure currently is.
According to Flood Re's published framework, each certificate would assess several dimensions of flood risk and preparedness. These include the property's level of exposure to flooding, the likely impact of different flood depths, and existing features designed to limit damage. Examples might include flood barriers, non-return valves, raised electrical systems or water-resistant flooring materials.
Certificates would also indicate the property's resistance to floodwater entry and its overall vulnerability to damage. Recommendations for further improvements would be included, offering homeowners a practical guide to reducing future losses.
The framework divides assessment into categories such as exposure, property characteristics and resistance. The intention is to produce ratings that homeowners can easily interpret while maintaining enough technical consistency for professional use by insurers, surveyors and lenders.
Testing begins in 2026 with phased rollout
Flood Re has confirmed that pilot projects will start in 2026, targeting areas where flood risk is particularly acute. Additional trials are planned throughout 2027. Early schemes will likely draw on the Environment Agency's Property Flood Resilience Framework, which already provides technical guidance on assessing and improving flood protection.
These pilots will examine how resilience can be measured, communicated and recognised across different contexts. Tests may extend to housing market transactions, insurance claims processes and new-build developments. The trials will also explore whether recorded resilience information can influence insurance underwriting and encourage homeowners to invest in protective measures.
Earlier planning documents from Flood Re suggested that certificates might eventually become mandatory when homes are sold or rented, mirroring the established approach for Energy Performance Certificates. Nevertheless, the current focus remains on validating the methodology rather than imposing legal requirements. Consequently, any wider rollout will depend on the results emerging from the pilot phase.
Why current flood risk information falls short
Flood risk data already exists in various forms. Environment Agency maps show which areas face higher exposure. Local authority planning records may indicate historical flooding. Insurance companies hold claims data. However, this information is rarely consolidated at property level in a way that homeowners or buyers can use to make informed decisions.
A household might discover their postcode lies within a flood zone, yet remain uncertain about how quickly damage would occur, which parts of the building are most vulnerable, or whether installing a flood door would materially reduce their insurance premium. Similarly, a buyer viewing a property may struggle to distinguish between a home with comprehensive flood defences and one with none at all.
The Government's FloodReady action plan describes Flood Performance Certificates as a potential solution to this fragmentation. By creating a single, standardised document, the scheme aims to make property-level resilience visible and actionable. Homeowners would gain clearer guidance on their specific vulnerabilities and the steps most likely to reduce damage. Insurers and lenders would receive consistent information that could support pricing, underwriting and lending decisions.
How homeowners could benefit from clearer resilience ratings
For individual householders, the most immediate value would be practical guidance on reducing flood damage. Certificates would identify which measures are already in place and which additional steps might be worthwhile. These could range from minor adjustments, such as repositioning vulnerable belongings, to more substantial interventions like installing flood doors, raising electrical outlets, fitting non-return valves or replacing carpets with water-resistant flooring.
A certificate could also help homeowners demonstrate their investment when selling a property. Flood Re has argued that enabling households to understand their risk, reduce it and provide evidence of protection represents the framework's primary benefit. In areas where flooding has occurred previously or where insurance availability is constrained, documented resilience could become a material factor in property transactions.
Flood Re is also exploring how resilience measures might be reflected in insurance pricing. Potential options include premium discounts for households holding a Flood Performance Certificate or completing an equivalent self-assessment. However, any pricing benefit would depend on insurers being confident that the measures documented in a certificate genuinely reduce claims costs.
Implications for insurers, lenders and conveyancers
Insurers could use standardised resilience information to differentiate between properties with similar geographic exposure but differing levels of actual vulnerability. Two homes on the same street might face identical flood probability, yet one could sustain significantly less damage if it has been fitted with barriers, raised electrics and water-resistant materials. A recognised certificate would allow insurers to price that difference more accurately.
For mortgage lenders, clearer property-level information could improve risk assessment, particularly in areas where flood risk affects insurability and long-term value. Properties that cannot be insured become difficult to finance. Therefore, lenders have a direct interest in understanding whether a home's resilience is sufficient to maintain insurance cover as climate projections change.
Conveyancers may eventually need to request certificates as part of standard pre-sale enquiries, much as they currently do with Energy Performance Certificates. This would add a new layer of due diligence but could also reduce disputes over undisclosed flood risk and help buyers make better-informed decisions.
Nonetheless, the impact on premiums and lending criteria is not automatic. Certificates would need to prove reliable, independently assessed and demonstrably linked to lower claims before insurers could confidently integrate them into underwriting models. The pilot phase will be critical in determining whether the proposed ratings meet these standards.
Outstanding questions around cost, consistency and liability
Several practical challenges will need resolution before any broader rollout can proceed. First, producing accurate ratings may require detailed physical surveys, especially for properties at significant risk. Survey fees could create a barrier for homeowners, particularly those with limited means who may also be least able to afford resilience improvements.
Second, assessors would need to work to common standards so that certificates remain comparable across properties and regions. Without consistency, the system risks becoming fragmented, reducing its usefulness to insurers and lenders who operate nationally.
Third, the framework must clarify liability if a rating underestimates risk or recommended measures prove inadequate. Homeowners and insurers will need confidence that certificates reflect genuine expertise and that assessors carry appropriate professional indemnity cover.
Fourth, making flood risk more visible could affect property values in vulnerable areas. Buyers may benefit from better information, but sellers in high-risk zones could face downward pressure on prices. This raises questions about fairness and whether additional support should accompany any mandatory certificate regime.
Fifth, data sharing arrangements will need careful design. Certificates would contain sensitive information about property vulnerabilities. Clear rules will be required to govern who can access this data and for what purposes, balancing transparency with privacy.
Finally, ratings must account for changing climate conditions. Flood risk is not static. Rainfall patterns, sea levels and river flows are all shifting. Certificates will therefore need regular review to remain accurate, adding administrative complexity and ongoing cost.
Connections to Build Back Better and wider resilience policy
Flood Performance Certificates sit within a broader policy shift towards reducing flood damage before it occurs, rather than simply responding after events. Flood Re's existing Build Back Better scheme already supports eligible households in installing resilience measures when repairing flood-damaged properties. This approach allows homes to be rebuilt to higher standards rather than simply restored to their original vulnerable state.
The new certificates would complement this initiative by creating a record of measures already installed and identifying further improvements. More importantly, they could encourage resilience investment before flooding happens, rather than only after a claim. If homeowners can see a clear rating, understand which measures would improve it, and know that insurers recognise those improvements, the business case for proactive investment becomes stronger.
However, information alone will not reduce flood damage. Homeowners also need access to qualified contractors, affordable finance and reliable technical advice. Our compliance support services help businesses navigate environmental and resilience requirements, particularly where regulatory expectations are evolving.
For the certificate scheme to succeed, it must translate into practical action. Otherwise, it risks becoming another form to complete rather than a tool that genuinely improves household resilience.
Core facts about the Flood Performance Certificate proposal
- Flood Re and the UK Government are developing Flood Performance Certificates to provide standardised assessments of property-level flood resilience.
- Pilot schemes will begin in high-risk areas during 2026, with further testing planned for 2027.
- Certificates would record flood exposure, existing resilience features, likely damage from different flood depths, and recommended improvements.
- The framework aims to serve homeowners, insurers, lenders and other professionals with consistent, comparable information.
- Earlier planning documents suggested certificates might eventually become mandatory for property sales or rentals, though current work focuses on validating the methodology through pilots.
- Flood Re is exploring whether resilience measures documented in certificates could attract insurance premium discounts.
- Outstanding questions include survey costs, assessor standards, liability arrangements, effects on property values, data privacy and how ratings will adapt to changing climate conditions.
What businesses in affected sectors should consider now
For SMEs operating in construction, property services, insurance supply chains or flood-risk consultancy, the pilot phase represents an opportunity to understand how the scheme might develop and where new commercial opportunities could emerge. Demand for flood resilience surveys, installations and ongoing maintenance could grow substantially if certificates become widespread.
Contractors offering retrofit services should consider whether their current capabilities align with the measures likely to be recommended in certificates. These might include flood barriers, non-return valves, tanking, raised electrics, water-resistant materials and drainage improvements. Building expertise in these areas ahead of wider rollout could provide a competitive advantage.
Property management firms and landlords should monitor developments closely. If certificates eventually become mandatory for rentals, portfolio-level resilience assessments and improvement programmes may become necessary. Early action could avoid later compliance pressures and help maintain insurability across property holdings.
Businesses involved in new-build construction should also pay attention. If the framework expands to new developments, resilience standards could become part of building regulations or planning requirements. Integrating flood-resistant design from the outset is typically cheaper than retrofitting protection later.
Finally, companies tendering for public sector contracts or working within supply chains where environmental and climate resilience criteria apply should consider how flood resilience might feature in procurement decisions. Our sustainable procurement guidance helps businesses understand and respond to emerging environmental requirements in tender processes.
The certificate scheme remains at an early stage, but its trajectory suggests that flood resilience will become more visible, measurable and commercially significant. Businesses that understand the framework early will be better placed to respond as it develops.
Where to find authoritative information on flood resilience
Flood Re publishes updates on the development of Flood Performance Certificates and related policy work. The Flood Re website provides information on current schemes, including Build Back Better, and explains how the organisation supports household flood insurance.
The Environment Agency maintains detailed flood risk maps and guidance on property-level protection through its official pages. These resources include the Property Flood Resilience Framework, which underpins much of the technical work behind the certificate proposal.
The Department for Environment, Food and Rural Affairs oversees national flood policy. Its FloodReady action plan sets out the Government's broader approach to household flood resilience and explains how Flood Performance Certificates fit within wider policy objectives.
For businesses seeking to understand the commercial and regulatory context, the long-term flood risk checker provides property-level data on flood probability from rivers, seas and surface water. This tool can help identify which sites or portfolios may be most affected by emerging resilience requirements.